Why an option can move differently from its underlying asset
Option sensitivities include time and volatility as well as direction.
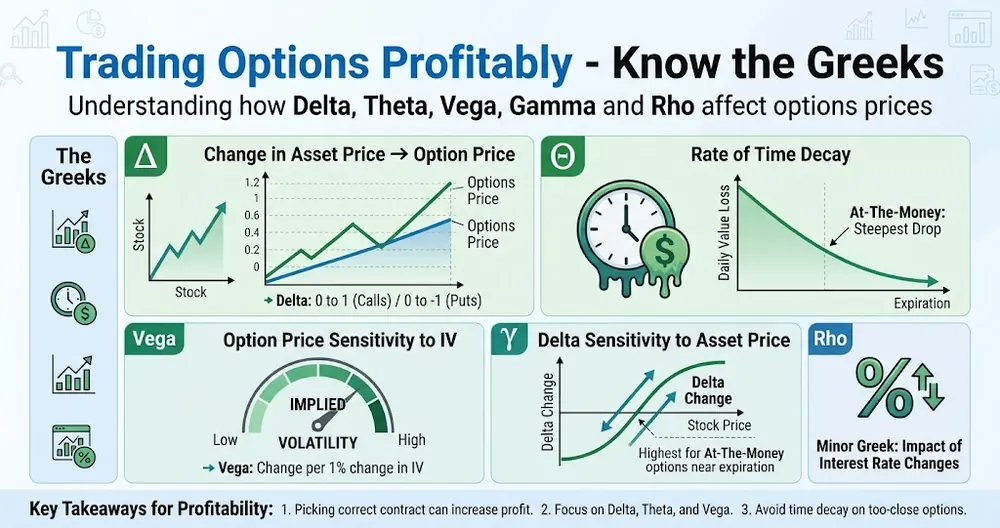
DailyForex explains why correctly anticipating a stock’s direction is not enough to understand an option’s price. The article introduces the Greeks as measures of how option value responds to changes in underlying price, time, implied volatility and interest rates. Several influences can act simultaneously.
Delta estimates sensitivity to the underlying asset, while gamma describes how delta itself changes. Theta relates to the passage of time, vega to changes in implied volatility and rho to interest rates. These are model-based sensitivities rather than guaranteed price changes under all market conditions.
The source uses the example of a call losing value despite a rising stock to show how time decay or falling implied volatility can offset a favourable directional move. This summary provides a map of those concepts rather than a profitable-options recipe or a recommendation to buy a contract.
Image source: DailyForex
Research sources & methodology
Original sources and publication references.
Сообщество